FXOpen Trader
Well-known member
UnitedHealth: Fundamentals Are Healing, Now the Chart Must Agree
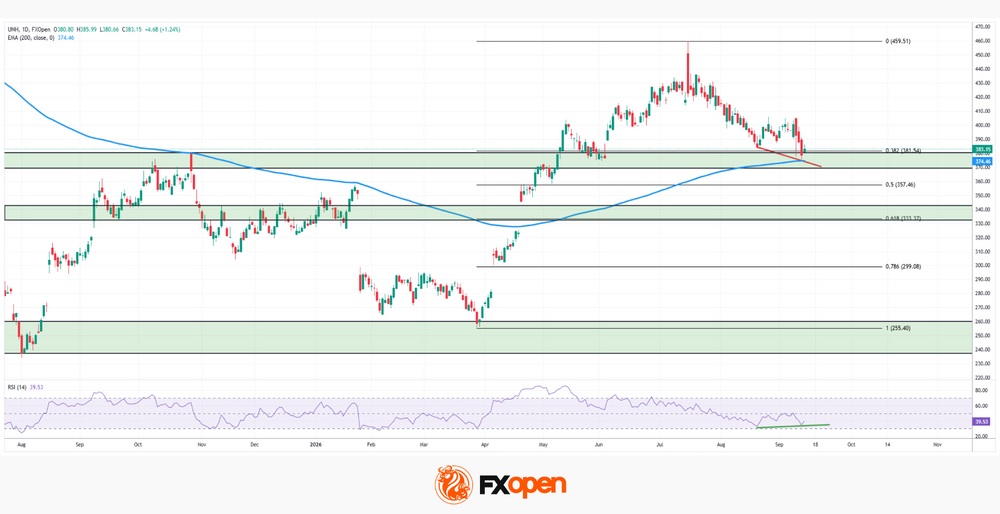
UnitedHealth finds itself in a genuinely split narrative right now, trading near $388, down about 15.9% from its 52-week high, even as the fundamental picture keeps improving. Q2 earnings beat expectations, with revenue of $112.03 billion, and the company followed through with a significant policy shift: lifting prior-authorization requirements on roughly 1,700 diagnostic codes starting October 1, a move that could meaningfully ease administrative friction with providers and support margins going forward.
Wall Street's conviction has only grown stronger as a result. Wells Fargo and Bernstein both reaffirmed Buy ratings this month, with price targets near $526 and $512 respectively, while the broader consensus, a Moderate Buy across 27 analysts, points to an average target of $456.56, implying roughly 17% upside from current levels.
The stock has nonetheless struggled to find sustained momentum, weighed down by lingering concerns over Medicare Advantage margin recovery and, more recently, the shock of losing a senior executive, an event that has triggered internal restructuring and closer scrutiny of governance and security practices.
The result: a company delivering genuinely solid operational improvement, but one whose stock price has yet to fully reflect it.
TO VIEW THE FULL ANALYSIS, VISIT FXOPEN BLOG
Disclaimer: This article represents the opinion of the Companies operating under the FXOpen brand only (excluding FXOpen EU). It is not to be construed as an offer, solicitation, or recommendation with respect to products and services provided by the Companies operating under the FXOpen brand, nor is it to be considered financial advice.
UnitedHealth finds itself in a genuinely split narrative right now, trading near $388, down about 15.9% from its 52-week high, even as the fundamental picture keeps improving. Q2 earnings beat expectations, with revenue of $112.03 billion, and the company followed through with a significant policy shift: lifting prior-authorization requirements on roughly 1,700 diagnostic codes starting October 1, a move that could meaningfully ease administrative friction with providers and support margins going forward.
Wall Street's conviction has only grown stronger as a result. Wells Fargo and Bernstein both reaffirmed Buy ratings this month, with price targets near $526 and $512 respectively, while the broader consensus, a Moderate Buy across 27 analysts, points to an average target of $456.56, implying roughly 17% upside from current levels.
The stock has nonetheless struggled to find sustained momentum, weighed down by lingering concerns over Medicare Advantage margin recovery and, more recently, the shock of losing a senior executive, an event that has triggered internal restructuring and closer scrutiny of governance and security practices.
The result: a company delivering genuinely solid operational improvement, but one whose stock price has yet to fully reflect it.
TO VIEW THE FULL ANALYSIS, VISIT FXOPEN BLOG
Disclaimer: This article represents the opinion of the Companies operating under the FXOpen brand only (excluding FXOpen EU). It is not to be construed as an offer, solicitation, or recommendation with respect to products and services provided by the Companies operating under the FXOpen brand, nor is it to be considered financial advice.


